


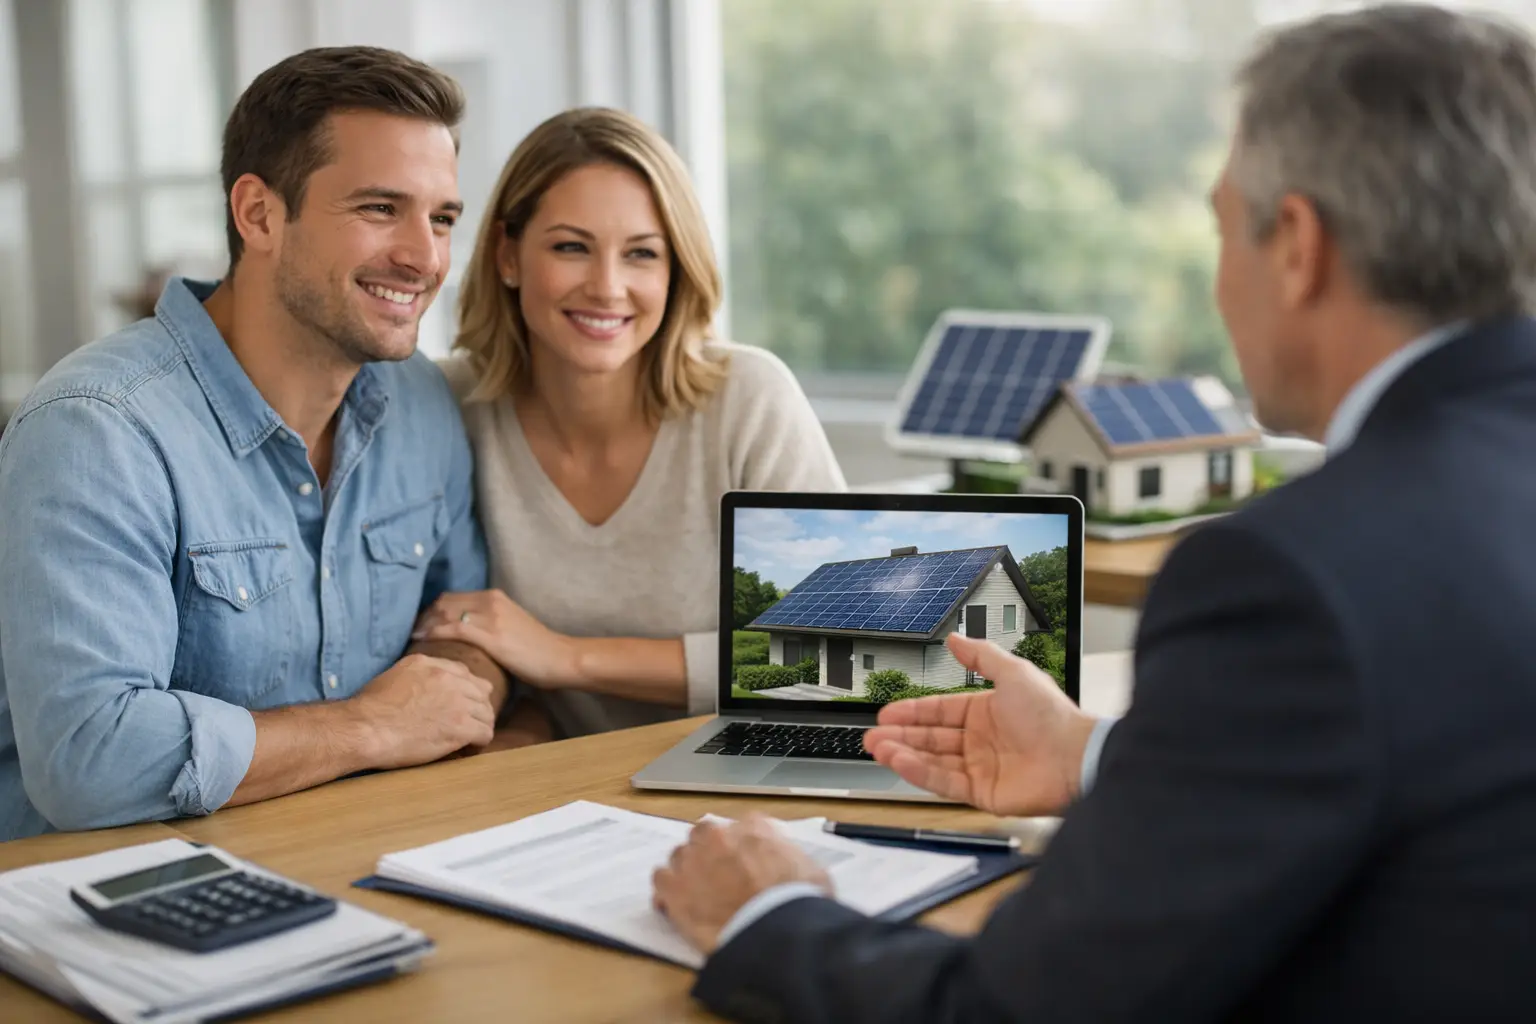
How to Qualify for Solar Financing With Confidence
A high electric bill can make solar feel urgent, but the first question is usually practical: Can I afford it? Knowing how to qualify for solar financing gives you a clearer path to lower energy costs without draining your savings. Approval is not only about a credit score. Lenders also consider your income, existing debt, property, and the project itself.
For homeowners and business owners across Southern California, the best first step is to understand what a lender needs before you apply. A little preparation can help you compare options with confidence and choose a monthly payment that fits your budget.
What Solar Financing Means
Solar financing lets you spread the cost of a solar energy project over time rather than paying the full amount upfront. Depending on the program and your goals, financing may cover solar panels, battery storage, electrical panel upgrades, roofing work needed before installation, and other related improvements.
A solar loan is often the most straightforward option. You own the system, make monthly payments, and may be eligible for applicable tax benefits. Some homeowners use a home equity loan or line of credit, while others may explore property-assessed financing where available. Businesses may have additional commercial lending or equipment-financing options.
The right choice depends on your cash flow, ownership goals, interest rate, term length, and whether your property needs more than panels alone. A lower monthly payment can be appealing, but a longer term may increase the total amount paid over the life of the loan.
How to Qualify for Solar Financing: What Lenders Review
Every lender has its own approval standards, but most review the same core information. They want to see that the applicant has the ability and history to repay the loan.
Credit history and credit score
Your credit score is one factor lenders use to assess risk. A stronger score can make it easier to qualify and may help you receive a better interest rate. That said, a perfect score is not required for every solar financing program. Some lenders work with a broader range of credit profiles, though the available terms may differ.
Before applying, review your credit reports for errors, pay down revolving balances if possible, and avoid opening several new credit accounts at once. Even a modest improvement in your credit profile can affect your options.
Income and ability to repay
Lenders typically look at verifiable income and your debt-to-income ratio. In plain terms, they compare your monthly debt payments with your monthly income to see whether another payment is manageable.
You may be asked for recent pay stubs, tax returns, bank statements, or other proof of income. Self-employed applicants can qualify too, but they may need to provide additional documentation. If your income varies by season or project, organize your paperwork early so the application process does not slow down.
Existing debt and monthly obligations
Car loans, credit cards, student loans, mortgages, and personal loans can all affect your application. High credit card balances may be more concerning than a long-standing mortgage paid on time, since lenders look at both the amount owed and your payment history.
Do not assume you need to eliminate every debt before considering solar. Instead, look honestly at your monthly budget. If your new solar payment is designed to offset a meaningful portion of your utility bill, it may be easier to manage, but lenders still evaluate the full payment obligation.
Property ownership and home condition
Most solar loan programs require the applicant to own the property where the system will be installed. Lenders and installers may also confirm that the roof, electrical service, and site conditions can support the project.
This matters because solar is not always a panels-only project. An older roof may need replacement first. A home with an undersized electrical panel may need an upgrade. Addressing these needs as part of one coordinated plan can protect your investment, but it can also change the total financed amount.
The size and design of the project
A lender will generally review the proposed project cost. That is why a thoughtful site evaluation matters. A system should be sized around your energy usage, roof space, shade, future electricity needs, and budget, not simply around the largest loan amount available.
For example, a family planning to add an electric vehicle or replace a gas appliance may need a system built for future consumption. A battery may be worthwhile for backup power or time-of-use rate management, but it raises the project cost. The best design balances resilience, savings potential, and a payment you are comfortable carrying.
Prepare Before You Apply
A prepared applicant can move from consultation to financing with fewer surprises. Start by gathering a recent utility bill, government-issued identification, proof of property ownership, and basic income documentation. If you are applying jointly, both applicants should be ready to provide the requested information.
Next, estimate your current electric spending. Look at more than one month if you can, since air conditioning and seasonal use can make bills vary. Your utility history helps show whether solar is likely to solve a real energy-cost problem and helps your consultant recommend an appropriately sized system.
It also helps to decide what you want the project to accomplish. Are you primarily trying to reduce utility costs? Do you need battery backup during outages? Is your roof nearing the end of its useful life? Clear priorities make it easier to compare financing offers without being distracted by a low monthly payment that does not actually meet your needs.
Compare the Full Offer, Not Just the Payment
A financing offer can look affordable while carrying costs that deserve a closer look. Ask for the annual percentage rate, loan term, total financed amount, monthly payment, dealer fees if any, and whether there is a prepayment penalty. You should also understand when the first payment is due and whether the payment changes after a promotional period.
If you expect to use a tax credit or other incentive to make a larger payment later, ask how that affects the loan. Some loans are structured around an anticipated principal reduction. If that reduction is not made, the monthly payment could increase after a set period. Never build your budget around an incentive until you have confirmed your eligibility with a qualified tax professional.
For business owners, compare financing with your expected operating costs, building ownership structure, and long-term plans for the property. Commercial projects can involve different underwriting standards and tax considerations than residential projects. A good proposal should make the payment structure understandable, not bury it in technical language.
If Your First Application Is Not Approved
A declined application is not necessarily the end of the road. It may mean the loan amount is too high, the lender needs more documentation, or your current credit and debt profile does not match that program’s guidelines.
Ask what can be improved before applying elsewhere. In some cases, paying down a credit card balance, correcting a credit-report error, adding a qualified co-applicant, choosing a smaller system, or waiting until you have more documented income can improve the outcome. Be careful about submitting many applications in a short period, since repeated credit inquiries can complicate your credit profile.
You can also revisit the project scope. If your roof needs work, bundling it with solar may be the right long-term decision. In other cases, completing urgent roof repairs first and financing solar separately may create a more manageable application. There is no one answer for every property.
Questions to Ask During a Solar Consultation
A trustworthy solar consultation should leave you with clear answers, not pressure. Ask which financing options are available for your credit profile, what documents you will need, and whether the proposed payment is based on an assumed tax credit or other future payment.
Also ask what happens if the roof, electrical panel, or permitting process reveals additional work. Understanding these possibilities before signing helps you avoid budget surprises. If Spanish is more comfortable for you or someone in your household, request a bilingual explanation of the proposal and financing terms. Major home and business decisions should be made in a language you fully understand.
Accessible Solar & Energy Storage helps property owners look at the whole project – solar, storage, roofing, and electrical needs – so financing can be discussed in the context of a plan that makes sense for the property.
A solar project should feel like a practical next step toward greater energy independence, not a confusing financial gamble. Bring your utility bill, your questions, and an honest picture of your budget to the conversation. With the right information and a financing option that fits, sunshine can become a more manageable part of your monthly plan.

Leave A Comment