


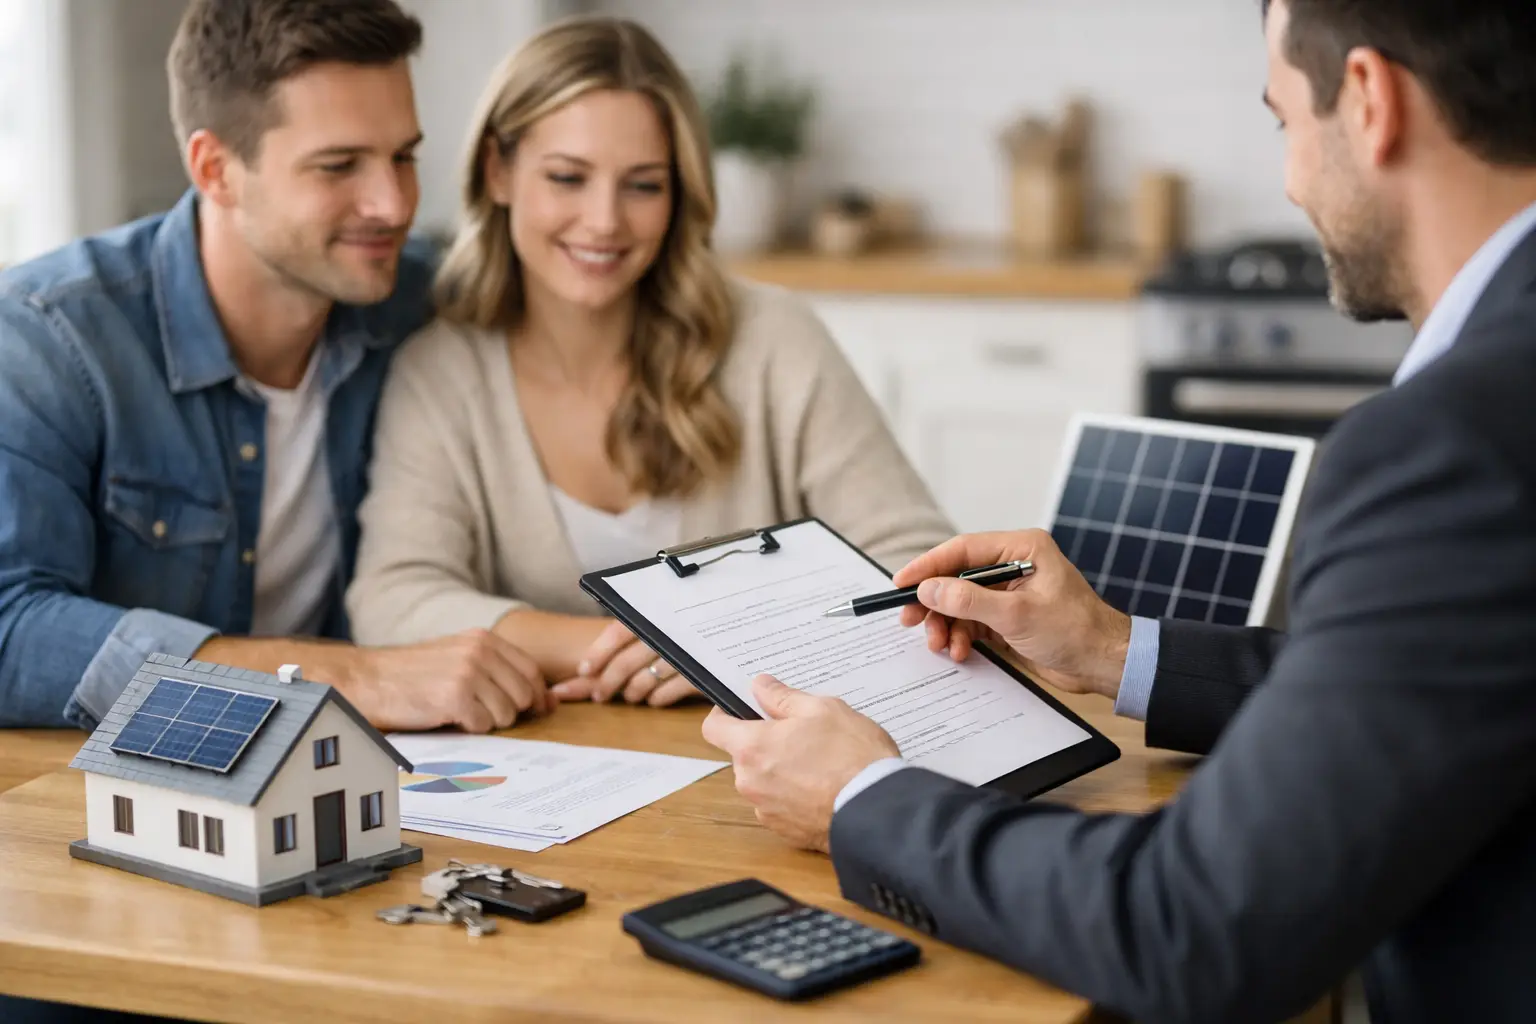
Home Solar Financing Approval Process
Most homeowners do not get stuck on solar because they dislike the idea. They get stuck because they are unsure what happens after they say, “Yes, I’m interested.” The home solar financing approval process is often the part that feels hardest to predict, especially if you are trying to lower your electric bill without taking on the wrong payment.
The good news is that approval is usually more straightforward than people expect. It is not magic, and it is not something you should have to figure out alone. If you understand what lenders look for, what documents may be needed, and where delays tend to happen, the process feels a lot more manageable.
What the home solar financing approval process actually covers
At its core, financing approval is a lender deciding whether to fund your solar project and under what terms. That includes your interest rate, payment amount, loan term, and sometimes the total project amount they are willing to approve.
For homeowners, this often starts after a consultation and a basic review of the property. The solar provider usually helps estimate system size, expected savings, and any related work that may need to be included, such as roofing, electrical panel upgrades, or battery storage. From there, financing is matched to the scope of the project.
This matters because lenders are not only looking at you as a borrower. They are also looking at the project cost and whether the payment makes sense in relation to your profile. A simple panel-only install may move through faster than a larger bundled project, but that does not mean more complex projects cannot be approved. It just means the details need to be clear from the beginning.
What lenders usually review
Most solar lenders start with the same core factors they would use for other consumer financing. Credit score is one piece, but it is not the whole story. Income, existing debt, payment history, and homeownership status often play a role too.
If you are wondering whether you need perfect credit, the answer is usually no. Many homeowners qualify with credit that is solid but not spotless. Some programs are more flexible than others, which is why the financing conversation should happen early instead of after the project is fully designed.
Lenders may also review your debt-to-income ratio. In plain terms, they want to see whether your current monthly obligations leave room for another payment. If your utility bill is already high, a solar payment may still make practical sense for you, but the lender will still use its own approval formula.
Property information can matter as well. You may be asked to confirm that you own the home, that it is your primary residence or an eligible property type, and that the address matches the application details. For some financing products, the lender may also want to know whether the home has any major title or occupancy issues.
How the process usually works from start to finish
In most cases, the home solar financing approval process begins with a consultation rather than a credit pull. That first step is where your provider learns about your goals, your utility usage, and whether you are looking only for panels or for a more complete energy upgrade.
Step 1: Project review and system estimate
Before financing is submitted, there is usually a proposed project scope. That might include solar panels, battery backup, roofing work, panel upgrades, or other related improvements. The more accurate this scope is, the easier it is to apply for the right amount the first time.
Step 2: Application submission
Once you are ready, a financing application is submitted with your personal and property details. Some lenders offer a quick pre-qualification, while others move straight into a formal review. You may be asked for basic information such as income, Social Security number, address, and housing status.
Step 3: Credit and eligibility review
The lender reviews your file and checks whether you meet its program requirements. Sometimes this produces an instant decision. Other times, the file goes into manual review, especially if income needs to be verified or if the project includes several bundled services.
Step 4: Conditional approval or request for documents
Approval does not always mean fully done. You may receive a conditional approval, which means the lender is willing to proceed once a few items are confirmed. That could include proof of income, a government-issued ID, recent pay stubs, tax returns, or clarification on the property.
Step 5: Final approval and financing documents
Once conditions are cleared, final loan documents are prepared for signature. At that point, the project can move forward with more confidence into design, permits, and installation scheduling.
Why some approvals are fast and others slow down
Some homeowners get an answer the same day. Others wait longer and wonder what went wrong. Usually, delays come from missing information rather than a problem with the borrower.
A mismatch between the application and property records can slow things down. So can incomplete income documentation or uncertainty about the total scope of work. If your project includes a new roof, battery storage, or electrical upgrades, the lender may need the contract structured clearly so it understands what it is financing.
Timing also depends on the lender itself. Some financing partners are built for speed. Others are more conservative and review files in stages. This is one reason working with a provider that helps coordinate financing support can save a lot of frustration. Instead of guessing what the lender wants, you have someone helping you package the project correctly from the start.
How to improve your chances before applying
The best thing you can do is come prepared. That does not mean you need to know every financing term. It means having a realistic picture of your budget, your credit standing, and the type of project you want.
If you can, check your credit before applying. Look for obvious issues such as reporting errors or overdue accounts that could affect the decision. If your debt is high relative to income, paying down a revolving balance may help more than you expect.
It also helps to gather documents early. If a lender asks for proof of income, you do not want the file sitting still while you search for paperwork. Clear communication matters too. If there are multiple owners on title, recent changes in income, or questions about occupancy, bring those up early.
For some households, the right move is not to rush. If your credit profile is right on the edge, waiting a short time to improve it may lead to better terms. The monthly payment difference can be meaningful over the life of the loan.
Approval is not just about yes or no
One of the biggest misconceptions is that financing approval is binary. In reality, there can be several workable outcomes. You may be approved for the full amount requested, approved with different terms, or approved for a smaller amount that changes the project scope.
That is where guidance matters. If one structure does not fit, another might. Maybe the original plan included battery storage and the better first step is solar only. Maybe a shorter term raises the payment too much, while a different loan structure makes the project more comfortable. The right answer depends on your goals, not just on getting any approval as fast as possible.
This is especially important for families and property owners trying to keep monthly costs predictable. Solar should help create long-term stability. Financing needs to support that, not strain it.
A local, people-first approach makes a real difference
For many homeowners across Southern California and Tijuana, financing feels personal because it is personal. You are not buying a gadget. You are making a decision about your home, your monthly expenses, and how much control you want over rising utility costs.
That is why a consultative approach matters so much. When a company takes time to explain the process, answers questions clearly, and helps coordinate the full project, the financing step becomes far less intimidating. Accessible Solar & Energy Storage works with that mindset because clean energy should feel within reach, not reserved for people who already know how every financing form works.
If you are thinking about solar, do not let uncertainty about approval stop the conversation before it starts. A good provider can help you understand what is realistic, what documents to prepare, and what path makes sense for your property. The clearest next step is often just asking questions and letting the numbers speak for themselves.

Leave A Comment